
Investment-Grade Traded Endowment Policies
What Are Traded Endowment Policies?
Traded endowment policies, also known as resale endowment plans, are procured by TES Capital from the original insurance policy owner when they choose to encash or surrender their policy. After ensuring that the policy is free from encumbrance, TES lists these endowment policies for takeover by sophisticated investors.
Traded endowment plans are gaining popularity in Singapore as a low-volatility, high-yield and easily-accessible asset class with flexible tenures and robust underwriting by blue-chip issuers. Suitable for portfolio diversification and long term wealth protection, they also provide a credible alternative to traditional investments in bonds, stocks and fixed deposits.
You benefit in several ways when you buy a traded endowment policy
Traded Endowment Policies in Singapore
Our pool of Grade A traded endowment policies and life insurance policies are procured from individual policy holders choose to surrender or encash their insurance policies.
When you buy over one of these resale endowment plans, you're investing in policies that are free from front-loaded distribution costs (agency fees). And once the policy matures, you'll receive a full cash pay-out from the insurer once the policy matures or the insured person passes away.
Depending on the remaining tenure of the policy, you'll enjoy up to 5% compounded returns.
How Traded Endowments Work in Singapore
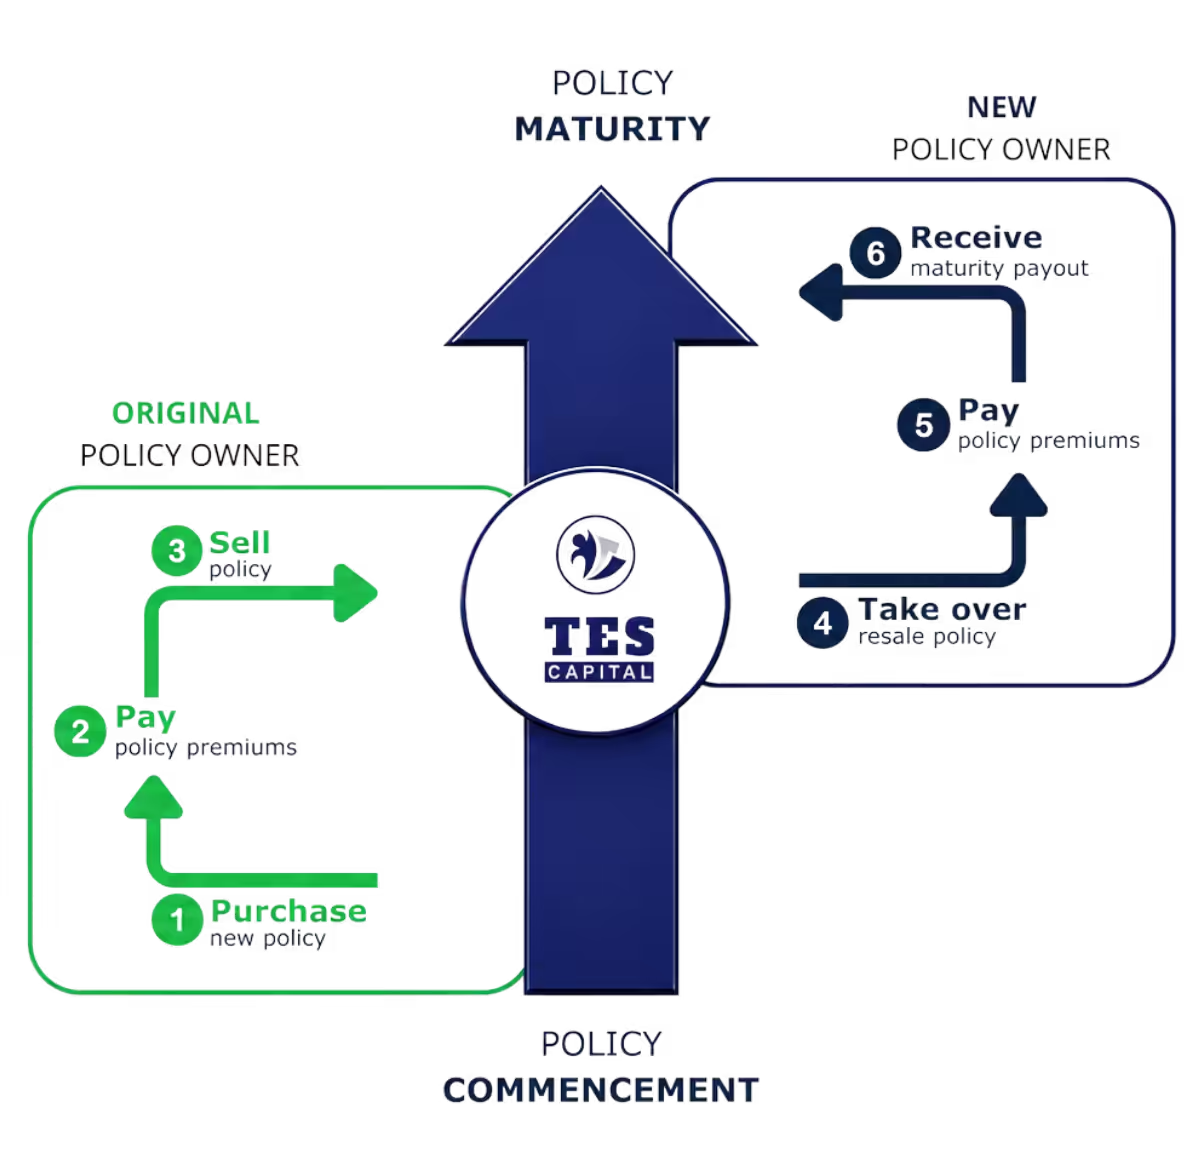
ORIGINAL POLICY OWNER
Step 1: Purchase new policy from insurer
Step 2: Pay policy premiums to insurer
Step 3: Sell policy to TES instead of surrendering to insurer
NEW POLICY OWNER
Step 4: Take over policy from TES
Step 5: Pay policy premiums to insurer
Step 6: Receive payout upon policy maturity
Traded endowment policies are acquired from existing policyholders and transferred to a new legal owner who becomes the beneficiary, receiving the full maturity cash payout when the policy eventually matures.

"My friend told me about TES and it was the right time as I was planning to open a fixed deposit account. Traded endowment plans are good for me as I would like to put my cash to good use while maintaining the assurance that I'll get my money back at the end.
You guys are doing a great job and service, keep it up!"
Ong Siew Fai, 33
Here's Why Singaporean Investors Love Traded Endowments
No health check
High levels of compliance
Excellent capital preservation
Higher return
No maximum age limit
Hassle-free process
Tax-free returns
Shorter time to maturity
TES is Singapore’s leading specialist in traded endowment policies with the largest AAA-grade traded endowment list in the market.
"I was doing research on Singapore savings bonds when I stumbled on traded endowments. After speaking to Shawn I felt confident to purchase 3 of these traded endowment policies as he carefully helped me select policies suitable for my needs.
I'm delighted to get the extra percentage returns which amounts to several thousand dollars of extra passive income each year. Highly recommended!"
Rebecca Lim Hui-En, 46
Who Should Consider Traded Endowment Policies?
Traded endowment policies are best suited for individuals who value clarity, defined timelines, and predictable financial outcomes.
Passive Income Investors
Individuals building long-term passive wealth choose traded endowment policies for their defined maturity schedules and insurer-administered payouts, which provide a clear pathway to future cash receipts.
Parents Planning for Education
Parents preparing for university funding use traded endowment policies to align maturity payouts with future education expenses, allowing them to plan confidently for significant costs.
Retirement Timeline Planners
Those approaching retirement rely on traded endowment policies to better align maturity dates with key life milestones, providing support for long-term financial readiness and stability.
Home Buyers and Life Milestone Savers
Individuals saving toward major goals such as property purchases or significant life milestones benefit from the defined payout timelines of traded endowment policies, which support disciplined and goal-focused planning.
Explore Resale Endowment Policies in Singapore
TES provides access to a range of traded endowment policies and resale endowment plans designed to meet different financial timelines and investment objectives. Each traded endowment policy is evaluated for transparency, projected returns, and alignment with investor goals.
Frequently Asked Questions
Traded endowment policies are also known as second hand endowments that procured from the original policy owner. After ensuring a clean title, TES makes these endowment policies available for take over by sophisticated buyers.
TES is the leading provider of traded endowment policies in Singapore and we are trusted by Singaporeans from all walks of life.
TES Capital Investments Pte Ltd is a company registered in the Republic of Singapore. We are the leading specialist in traded endowment and life insurance policies trusted by Singaporeans from all walks of life.
We specialise in assisting Singaporeans who looking to surrender their insurance policies. TES has become a trusted helper to these discontinuing policy holders. We offer these policies for takeover after ensuring that these policies have a good title.
The transfer of ownership is done through absolute assignment and all the necessary paperwork is done at the office of the insurance company in the presence of their officers. The procedure is simple and fully transparent.
An Absolute Assignment is the transfer of the ownership (all rights, benefits and liabilities) of a policy completely from the existing policyholder (Assignor) to the new policyholder (Assignee) without any terms and conditions.
A policyholder can transfer the rights on his policy to another person/entity for various reasons.
This Absolute Assignment process is governed under the Policies of Assurance Act (Chapter 392).
If the Assignor or Assignee is a natural person, he or she must be at least 21 years old, of sound mind, not an undischarged bankrupt and not entering into Absolute Assignment under duress.
The Monetary Authority of Singapore (MAS) has on 30 March 2015 issued a Notice to Life Insurers stating, among other things, that assignment of the benefits of a life insurance policy is allowed to a person other than the insured.
In order for Insurers to facilitate the Absolute Assignment process, both the Assignor and Assignee are required to complete and submit a Notice of Assignment together with other required supporting documents and forms. This Notice of Assignment can be downloaded from most of the Insurers' websites directly.
Upon completion of the Absolute Assignment process, the Insurer will send a written acknowledgement of Notice of Assignment to both Assignee and Assignor.
Yes you can. You can perform another absolute assignment at the office of the insurance company to effect the next transfer.
You pay TES an initial sum by bank transfer or cheque for the policy you’re taking over. You will then become the new policy owner and any future premium payments will be made directly to the insurance company.
The insurance company will require that any nomination or beneficiary be removed prior to an assignment. The policy you take over will be free from any nomination or beneficiary.
All rights and benefits belong to the policy owner and only the policy owner can provide the insurance company with a valid discharge. The insurance company will contact the policy owner for a pay-out should they become aware that the person insured has passed on. If this does not happen, the policy will continue on to maturity.
The insurance company will notify the policy owner by mail approximately one month before the maturity date of the policy. Payment is usually effected by cheque issued by the insurance company and sent to the registered address of the policy owner, although other forms of payment can be arranged.
The policy will be treated as one of your assets, similar to other investments, property, or money in bank accounts that you may own. Upon your demise, the policy may be assigned, surrendered or sold to another party by the executor of your estate.
There are currently no MAS administered regulations which govern the sale, purchase and distribution of traded or resale endowment or whole life insurance policies. As such, TES Capital Investments Pte Ltd is not required to be licensed by MAS.
Traded endowment plans are viewed as an alternative to fixed deposits in Singapore because they typically offer longer remaining tenures and predefined maturity values, reducing reliance on short-term interest rate cycles.
Compared to fixed deposits, which usually need to be renewed every few months, traded endowments allow investors to hold through to maturity while remaining within a capital-preservation-focused structure backed by insurance policies.


