
A fixed deposit in Singapore is often the first choice for investors seeking capital protection and predictable returns. Banks regularly promote competitive Singapore FD rates, making fixed deposits appear safe and straightforward.
However, when inflation rises or bank FD rates fall, many investors start comparing alternatives that can deliver higher returns without taking equity-level risks. One such option is traded endowment plans, which function as a conservative, income-focused alternative to fixed deposits.
Fixed Deposit Rates in Singapore
Fixed deposit rates in Singapore vary by bank, tenure, and promotional period. Most Singapore FD rates are offered across short tenures ranging from three to twelve months, with higher headline rates often tied to limited-time campaigns or larger deposit amounts. While fixed deposits provide capital certainty, returns are typically modest, which is why investors frequently compare the best FD rates in Singapore rather than locking into a single provider long term.
Why Fixed Deposits MAY Not Be Enough Today
Fixed deposits in Singapore are designed for short-term capital parking rather than long-term wealth preservation.
In an environment where inflation can outpace fixed deposit returns, investors who rely solely on FDs may find their purchasing power gradually eroded. As a result, many investors begin evaluating alternatives that maintain capital stability while offering more predictable returns over a longer horizon than standard fixed deposit cycles.
Singapore’s Trusted Alternative to Fixed Deposits
TES Invest offers traded endowment plans as an investment-grade alternative to a traditional fixed deposit in Singapore. These plans appeal to investors who prioritise capital preservation while seeking potentially higher annualised returns than standard bank FD rates.
Unlike fixed deposits, traded endowment plans involve taking over existing insurance policies at a discount to their maturity value. This pricing structure allows investors to lock in a defined payout while maintaining a conservative risk profile.
Traded endowment plans have gained traction as a low-risk and accessible alternative to traditional investments such as bonds, equities, and fixed deposits. They are commonly used by investors for portfolio diversification and long-term wealth preservation, especially when fixed deposit rates are no longer keeping pace with inflation.
Also known as Resale Endowment Policies (REPS), investing in Traded Endowments brings you several benefits!
Blue-chip issuers
Singapore institutions governed by MAS and insured under the Policy Owners' Protection (PPF) Scheme!
Returns up to 5%
Returns up to 5% are better than new endowment plans, fixed deposits or Treasury bills!
Shorter time to maturity
Your choice of short duration plans that mature in 3 to 6 years or even less!
Low distribution costs
Save on hefty front-loaded commissions which are paid on 'brand new' endowment plans!
No health check
No health questionnaire or checks are required when you purchase traded endowments!
No maximum age
Buy with confidence without a restrictive maximum entry age to limit your investment!
You can check out all our Resale Endowment Plans 'live' in our updated TES List now!
... or scroll down to learn more!
Fixed Deposit vs Traded Endowment Plans in Singapore
The comparison below outlines key structural differences between fixed deposits and traded endowment plans in Singapore, including tenure, return characteristics, and protection frameworks.
Feature | Fixed Deposit | Traded Endowment |
|---|---|---|
Capital Protection | Yes | Yes |
Returns | Low to moderate | Potentially higher |
Typical Remaining Tenure | 3–12 months | 3–6 years |
Insurance Protection | Bank guarantee limits | PPF Scheme |
Inflation Risk | High | Low |
Why Invest in Traded Endowments in SingaPOre?
PROVEN
Buying traded endowment policies instead of purchasing a new insurance policy has been used by sophisticated investors to preserve wealth for many years.
SAFE
The life and endowment policies you buy over are underwritten by leading Singapore insurance companies which are governed by the Monetary Authority of Singapore.
EASY
Buying traded endowments requires no active monitoring of market movements, no technical analysis, no advanced financial knowledge, and no entry requirements for buyers.
"When I first came across traded endowments, I was quite curious as to see if it was really an alternative to fixed deposits.
After spending many hours studying the materials from TES and the MAS website, as well as speaking to officers from AIA and Prudential, I felt confident to proceed with a small traded endowment investment with a very short tenure (6 months to maturity).
I've just received the full payout from the insurer and in less than one year the returns are much higher than expected and with such low risk! Just writing in to say, thanks Shawn and team for the opportunity, as you can see I've taken up another 5 resale policies from you."
Thank you so much for sharing this wonderful opportunity, I can't thank you enough. God bless!
Mdm Wang Ping-En
Singaporean, 55
Here's Why Singaporean Investors Love Traded Endowments
No health check
High levels of compliance
Excellent capital preservation
Higher return
No maximum age limit
Hassle-free process
Tax-free returns
Shorter time to maturity
TES is Singapore’s leading specialist in traded endowment policies with the largest AAA-grade traded endowment list in the market.
How Traded Endowments Work in Singapore
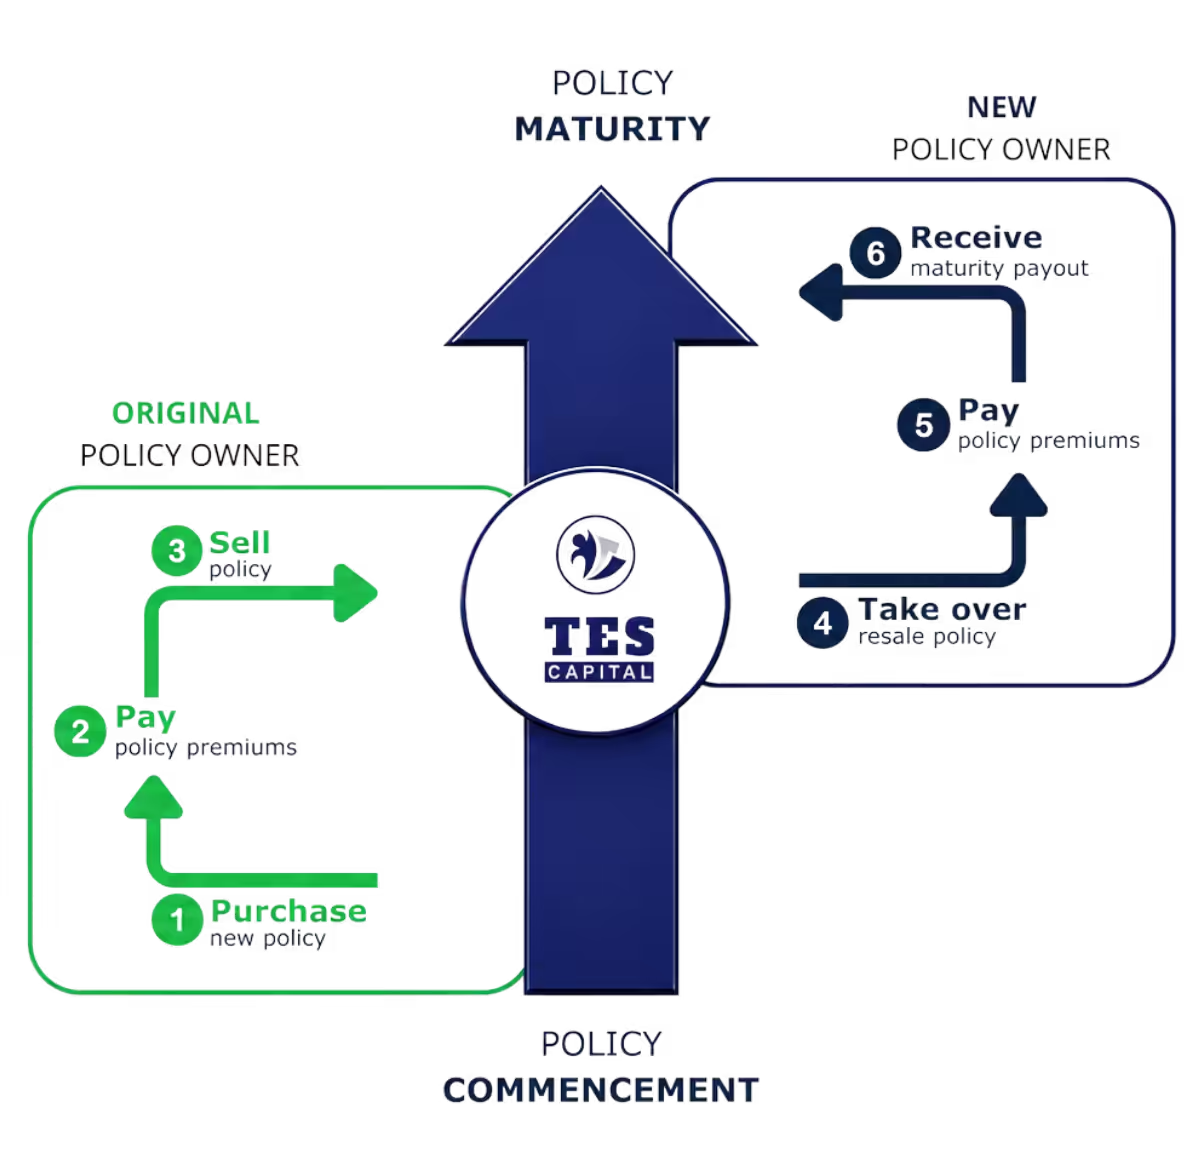
ORIGINAL POLICY OWNER
Step 1: Purchase new policy from insurer
Step 2: Pay policy premiums to insurer
Step 3: Sell policy to TES instead of surrendering to insurer
NEW POLICY OWNER
Step 4: Take over policy from TES
Step 5: Pay policy premiums to insurer
Step 6: Receive payout upon policy maturity
Why Investors Trust TES Capital
TES is Singapore's #1 specialist in Traded Endowment Policies, respected for honesty, professionalism and transparency. The firm has facilitated the transfer of traded endowment policies across major insurers and maintains one of the largest curated lists of investment-grade traded endowments available in the market.
Every policy offered is screened for title clarity, insurer standing, and structural suitability before being made available to investors. Ownership transfers are conducted through absolute assignment at the insurance company, ensuring a transparent and fully documented process aligned with Singapore market practices.
Disclaimer:
This article is published by TES Invest for general educational purposes only and does not constitute financial advice or recommendations. Information is sourced from publicly available materials from MAS, MoneySense, and major insurers as of 2026. Please consult a qualified financial adviser before making any purchase decisions.


